Visit us at our new home!

For new daily content, visit us at our new blog: http://www.acrinv.com/blog/

Thursday, January 7, 2010

Daily Insight

U.S. stocks bounced above and below the cut line several times yesterday, eventually rallying just enough in the final minutes for the broad market to close fractionally higher – the NASDAQ Composite failed make it back to the black but its holding on to most of Monday’s big gain.

The day’s economic data wasn’t enough to give the market a clear directive as the latest releases on housing and the service sector were not compelling.

The dollar moved significantly lower, with most of its decline occurring after the minutes from the latest FOMC meeting showed interest among some policymakers in expanding their mortgage-security purchase program. Print more dollars…well that’s so 1980s, they actually electronically deposit the funds into accounts. Either way it’s all the same, dramatically increase the supply of something and the price will trend lower.

Basic material and energy shares helped to buoy the market. The index that tracks material shares gained 1.52% and energy shares rallied 1.03%. Crude prices rose to the $83 handle even as the weekly energy report showed stockpiles increased 1.3 million barrels -- expectations were for supplies to fall 1.6 million barrels. Such a substantial difference would have normally sent crude price lower, but the lower dollar drove the trade in the pits.

Market Activity for January 6, 2010
Mortgage Applications

The Mortgage Bankers Association reported that its mortgage applications index rose 0.5% in the week ended January 1 after two weeks of large declines – apps slid 22.8% in the prior week and 10.7% the week before that.

Purchases rose 3.6% in the latest week after declines in the previous two weeks of 4.0% and 11.6%, respectively. Refinancing activity fell 1.6%, which also followed big declines in the prior two weeks – down 30.5% and 10.1%

The rate on the 30-year fixed mortgage rose to 5.18%.

Weak Moves into the Paint Get Rejected

You may have noticed the tariffs Washington is levying on Chinese steel. Well, the old Chinese may come back with a little counter of their own by further reducing their purchases of Treasury securities. The disturbing policy events just keep building; I don’t think Washington wants to get into this game of chicken right now. Picking trade fights is a very dangerous endeavor, especially so during a time of economic fragility – in addition it increases costs upon an already burdened consumer. But the degree to which such activity can adversely affect things is heightened that much more as we engage in massive deficit spending. The last thing we want is to do is something that may curtail future bids for government debt.

When the Fed fully completes their $1.25 trillion in mortgage-backed security (MBS) purchases that is going to reduce demand for government debt as well – as PIMCO has explained, they and others are selling their MBS to the Fed and buying Treasuries with the proceeds. The Fed’s printing press strategy is providing the demand for the Treasury market and keeping rates low. So that’s one demand source that will evaporate (if the Fed doesn’t come back and buy up even more MBS when housing runs into trouble again post April). Implementing policies, such as disputes with trading partners, that could cause other sources of funding to disappear will sting.

Some of you may have noticed that earlier this week China pulled a Dikembe Mutombo and stuffed U.S. attempts to levy sanctions on Iran – I’m sure the tariffs on Chinese steel made their decision that much easier.

ADP Employment Change

The preliminary employment report out of ADP, the business outsourcing solutions firm, estimated that 84,000 jobs were cut in December. This is quite a bit worse than what the market expects via Friday’s official jobs data, which is for no change -- and many expect a mild increase.

ADP has been off by a large margin lately, overstating the employment losses by roughly 100K per month on average since August, prior to that ADP was doing a pretty good job of predicting the jobs data when the labor market was in full-fledged freefall late-2008/early-2009. As a result of the degree of inaccuracy of late, I’m not sure what good the ADP numbers are right now, but we’ll go over them quickly nonetheless.

On the headline number, the 84,000 decline in private-sector payrolls ADP expects is the smallest rate of decline since March 2008.

In terms of industries, ADP has goods-producing sectors shedding 96,000 for the month, which is a significant deterioration (if accurate) as the official numbers had these payrolls down 69K in November. (Goods-producing, manufacturing and construction, jobs have shed 3.5 million positions over the past two years – most of which are permanently gone or will take a long time to come back. The auto sector alone has slashed 840,000 and construction 1.5 million. The auto jobs are permanently gone as the industry had been living with bloated expenses as if the Big Three had hopped into the DeLorian and traveled back to the 1950s; some significant percentage of construction jobs have been eternally extinguished -- until at least the next housing bubble arises, which will be a while. Of course, we could create – I don’t have a number, but a lot – of high-paying manufacturing jobs if we implemented a sensible energy policy that tore down omnipresent restrictions. But this appears to be heresy to too many people, so scratch that repulsive thought.)

The service-providing sector actually added 12,000 positions in December, according to ADP. This would also show deterioration as the official data had 58K added within the service sector in November.

We’ll see how it turns out when the Labor Department releases the figures on Friday. We’ve talked about how monthly job growth will emerge over the next few months, a point we first mentioned following the October jobs data. It may be a little too early to expect a boost in jobs for December, but February and March should be good to go for a positive reading. And expect some big numbers via government employment, especially as they add 2010 census workers. From there it will take 100K-plus per month for an extended period to slowly bring the jobless rate lower.

ISM Service-Sector

The Institute for Supply Management’s latest gauge of service-sector activity was pretty much a snorer, and failed to confirm a rebound has taken hold within the service-providing segment of the economy. The index came in at 50.1 (50.5 was expected) for December after slipping to contraction mode in November with its print of 48.7. The line of demarcations between expansion and contraction is 50.
With all of the talk about the V-shaped recovery, one would think ISM Service would be able to at least hit 52 and hold there – this is the average for the 2002 period, which was when the recovery from the 2001 downturn began and it was a weak one with just 1.95% GDP growth for the year. (When things really began to accelerate in 2003 – 3.85% GDP for the year – ISM Service averaged roughly 55.) Unfortunately, this data only goes back to 1997 so we can’t match against other expansions.

The best part of the report came via the inventory measure, which moved to expansion mode for the first time since August 2008 -- just before the credit trouble deteriorated to crisis mode. The figure came in at 51.5 and does offer some hope that business confidence within the service sector improved.

Ben Gay

The FOMC released the minutes from their December 16 meeting but these notes are becoming less useful as the Bernanke Fed offers more updated messages via speeches. We’ve talked about this for some time and there is zero doubt that Bernanke uses speeches as his primary beacon with which to send the market signals as to their latest views.

The latest signals have come via the three speeches delivered early this week (Bernanke and Vice Chairman Kohn addressed the American Economic Association on Sunday and Fed Governor Duke followed up with her comments to the Economic Forecast Forum on Monday. They were all very dovish, expressing the need for policymakers to keep the emergency level of rates in place to support the financial sector, housing, and the economy in general.

The only additional news the minutes provided, as touched on above, was that a few policymakers favored increasing and extending asset purchases – and some people think the financial system, the housing market and economy have healed? Only looks that way because of massive support, the economic crutches the government has provided. If the economy were in normal recovery mode then would there be any discussion of extending quantitative easing (QE), policy that will make things much more difficult for when they do eventually have to unwind it all?

“It might become desirable at some point in the future to provide more policy stimulus by expanding the planned scale of the large-scale asset purchases and continuing them beyond the first quarter,” as the minutes showed some FOMC members suggested. They don’t exactly sound sanguine. Rather, some members appear to be pretty worried what happens to housing and the banking system when the Fed stops buying securities.

For new readers I’ll repeat, the Fed is in a box. If they stick to the current QE (asset purchases) expiration they know yields will rise, another round of difficulty housing will endure and the likely damage to riskier asset prices. But if they extend QE for fear of this all the US $ will test its very near-term lows and possible the all-time nadir, commodity prices will continue to move higher and possibly unmoor inflation expectations. While nominal stock prices may continue to go higher for a while, even a stock market that is jacked up on easy money will have to respond to the other damages a ballooning Fed balance sheet (money printing) will have on longer-term economic conditions. It’s quite a quandary they find themselves in.

What is for sure, Helicopter Ben is living up to this pejorative name some have given him. (The name arose from his 2002 speech about deflation in which he stated the government can produce as many U.S. dollars as it wishes at no cost. Maybe a more appropriate term for Bernanke, if they do go and extend QE, is B-29 Bomber Ben – or more concisely put: Ben Gay.


Have a great day!


Brent Vondera, Senior Analyst

Wednesday, January 6, 2010

Daily Insight

U.S. stocks struggled for most of Tuesday’s session after a much-worse-than-expected pending home sales report showed the underlying fragility of housing; however, the broad market did manage a decent gain and the NASDAQ Composite rallied in the last half-hour enough to eke out a fractional gain. The housing weakness boosted the view that the Fed will keep rates floored for quite a while still – I know we keep talking about this but it remains such a huge theme for traders that it must be mentioned.

The latest factory orders data showed very nice activity occurred in November, but it’s not enough to offset the housing news and begin to worry those in riskier assets that the Fed is about to begin the Great Unwind. I for one want to believe this manufacturing rebound is for real, but it seems so transitory – beefed up by auto assemblies that are likely to be short-lived and housing construction that looks ready to roll over again. Electronics production, which may be the only lasting story as firms must at least manage business-equipment orders to maintenance levels and even maintenance levels of purchases looks good compared to where we’re coming from, also boosted the factory orders data.

Everyone understands, or should, that housing is a central issue for the banks and that is going to keep Bernanke & Co. frozen from even gently raising short-term rates – unless forced to by the bond vigilantes pushing the long-end of the curve higher. The industry has to deal with very deep credit issues such as high credit-card and mortgage delinquencies. If home sales retrench again that will put pressure on prices and lead to additional loan problems for the banks.

Remember, we have three-seven million properties that are going to enter supply (the low end of that estimate would double the current homes available for sale figure) as the foreclosure process has been delayed due to mortgage modifications that are proving to be counter-productive. Any trouble on the sales front is going to exacerbate this situation. On top of that, there are roughly 25% of mortgages underwater (higher than the property’s value), with 5.3 million borrowers at least 20% underwater, according to industry analysts. One has to expect that at least a significant number of these troubled loans are going to be foreclosed upon. It is difficult to see how credit is going to expand; certainly it appears that lending has no business expanding until the delinquency and default rates begin to trend lower.

Treasury security prices rallied hard, the yield (which moves inverse to price) fell 6 basis points to 3.76% as there was some run to safety.

Market Activity for January 5, 2010
Factory Orders

The Commerce Department report good news in that factory orders rose 1.1% in November, double the expectations of a 0.5% increase.

New orders for manufactured goods have now risen seven of the last eight months. Excluding transportation, new orders increased 1.9%. New orders for durable goods (those meant to last at least three years) are up two of the past three months, increasing 0.4% in November – unchanged from the previously published increase via last week’s durable goods orders reading. Computer & electronic products, also up two of the past three months, showed the largest increase of all segments for the month, surging 4.9%.

Inventories of manufactured goods were up 0.2%, marking the second month of increase. Inventories of durable goods fell though for the 11th consecutive month, down 0.3% -- transportation equipment inventories fell 0.4%, leading the decline in durable stockpiles. Stockpiles of nondurable goods rose 0.9%, the second month of increase – led by a 4.2% rise in petroleum and coal products, so there is a little depressed demand factor in this reading.

The only real negative in the report came by way of the unfilled orders figure, down 0.7% for the month – lower for 14-straight month, the longest stretch since this data began in 1992.

Pending Home Sales

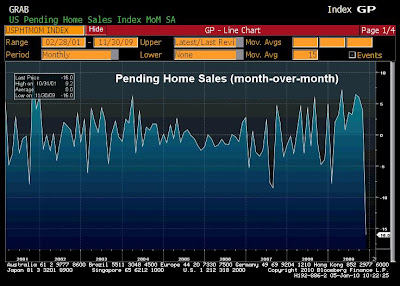
The National Association of Realtors reported that pending home sales got slammed in November, falling 16% compared to October’s activity – the first decline in 10 months. The number was expected to decline just 2.0%. This plunge will show up via existing home sales for part of December, but mostly within January’s results. Pending home sales are contract signings for previously-owned homes. Those sales are not officially counted until the contracts close; the signing to close process is taking about six weeks on average.


It was unclear to home-borrowers, prior to the November 4 promulgation, whether or not the tax credit would be extended so there was a rush during August, September and October to get in before the deadline, which caused a respite in sales that may extend for a couple of months – it pulled sales forward. If existing home sales officially drop by this degree that pending sales is predicting (official number is released January 25) it will erase the boost that’s occurred over the previous two months, and then some.

We should see sales rebound by early spring as that subsidy has been extended through April, although I’m not sure one should expect the tax credit to invigorate sales to the degree it did the first go around. What this pending sales data for November suggests is the degree to which sales will decline post-April 30 when the credit expires. What we are doing, just as is the case with all of the other government support, is delaying the inevitable.

By region, the Northeast and Midwest were the hardest hit as contract signings fell 25.7% in each location. The South saw contract signings decline 15%. The West held up very well, as pending sales fell just 2.7% -- this is the area with the most distressed properties and since these properties have accounted for a third of all sales over the past few months the relative out-performance for the region should not be surprising.

From a year-over-year perspective, pending home sales are up 25.1% in the West, up 21.3% in the Northeast, up 17.1% in the South and higher by 14.2% in the Midwest.

Vehicle Sales

Total U.S. vehicle sales came in better-than-expected for December, registering 11.23 million units at a seasonally-adjusted annual rate – 11.00 million was expected. For the year, vehicle sales finished at 10.425 million, down 21% -- the lowest annual figure since 1982. The year ended a heck of a lot better than things looked just a few months back, but dealers offered large incentives, interest rates remained extremely low and loan-to-value ratios were obscenely high – 93% as of the latest consumer credit data.

Ford’s sales jumped 32% during December from the year-ago level (down 15.4% for all of 2009) as the firm has seen a nice turnaround of late thanks to good products and possibly buyers’ attraction to the only U.S. maker that refused to take a government handout. GM saw sales fall 5.6% for December, even as they offered the deepest discounts. GM’s sales fell 29.7% for all of 2009.

Honda and Toyota made a good run of it in the final months of the year, but even those names saw sales fall 19.5% and 20.2%, respectively for the year.

Have a great day!


Brent Vondera, Senior Analyst

Tuesday, January 5, 2010

Daily Insight

U.S. stocks rallied on the first trading session of the year as traders returned to work with a sense of euphoria. Oh, and a speech by Fed Chairman Bernanke on Sunday to the American Economic Association suggested that the easy-money train will roll on for quite a while. Barton Biggs summed it up well while explaining his bullish fervor: “I don’t know what’s going to happen in the second-half of [2010]. I’m just saying that in the next three to six months the economy is going to keep recovering and stocks are going to go up again.” The bulls may be more short-sighted than anytime in the past 30 years.

Yesterday felt a lot like the final three quarters of 2009 as the same trades prevailed: stock, commodity, Treasury prices all up; the dollar down.

The day’s economic data was mixed as the latest manufacturing report posted its fifth-straight month in expansion mode, while the latest construction-spending reading fell for a seventh-straight month.

Crude oil rose well into the $81 handle yesterday on a combination of events: very cold weather across the country, an array of pretty strong global manufacturing reports and the Bernanke speech.

(I found it interesting that the Shanghai market closed lower by 1% during their Monday session even after another good factory report from that country – another sign that what’s good is bad as stock prices around the globe are being fueled by rock-bottom interest rates. This conditioning, also particularly true for the housing market, may just cause more troubles than would otherwise be the case when rate rise even mildly from these levels.)

Market Activity for January 4, 2010
Maybe the 2012 Prediction Isn’t So Crazy (No not that the world will end, the other prediction)

As mentioned above, Mr. Bernanke delivered a speech this past weekend in which he stated that regulations must be used to prevent bubbles, Fed tightening is just an “option.” Does this mean he’s setting the tone for the Fed will wait a very long time before they begin to unwind the unprecedented monetary easing policy that remains in place? Does this give credence to Federal Reserve Bank of St. Louis President Bullard’s prediction that the FOMC (also an estimate by Goldman Sachs) won’t raise fed funds until 2012?

He certainly denied that interest rates were the cause of the housing bubble, not the first denial as he’s stated this before. If interest rates didn’t cause the housing bubble, or more appropriately termed the debt bubble, I don’t know what did. He says it was a lack of regulation and the monitoring of this regulation but while some regulation is necessary it has never stopped crises. Besides, the lack of lending standards follow borrowing excesses, they don’t cause them. Undoubtedly, very easy credit certainly exacerbates things but extremely low interest rates for a long period of time is the origin. It is a very low interest-rate environment that gets the ball rolling.

The Fed needs to understand that human nature goes wild when incited by bad policy decisions by the FOMC – like consumers and institutions are not encouraged to take on more debt when fed funds is below the rate of inflation? Please. Everyone wants in when money is “free”, and it was essentially free when one could get an ARM at close to zero in real terms.

And it would be wrong to let Congress off the hook. Rolling the dice, to paraphrase Barney Frank’s now famous words, with Fannie and Freddie and many years of prodding lenders to extend credit to high-risk borrowers is another major cause of the problems we now face. The alternative mortgage products that Mr. Bernanke cites as “quite important” and “a key explanation” for the housing mess were created in response to pressures from Congress to boost home ownership. Congress had absolutely no problem with loans that minimized payments to the detriment of principal and dispatched the down payment, in fact they encouraged it…until home prices began to fall and these mortgages (turned into investment securities) became toxic. Again though, without super-low interest rates there is no incendiary device.

The fact that the Fed fails to understand this (or is it just that they are unwilling to raise rates even a smidge because they know the additional burden that will result with regard to servicing the massive debt the government is incurring) means that they should be stripped of their interest-rate mechanism; the market needs to determine rates if the Fed is going to deny such obvious connections. There is no doubt that debt bubbles, misplaced assessments of risk and commodity-price spikes are directly associated with excessively easy monetary policy. To deny this reality is like obstinately arguing the universe is geocentric. Of course, Galileo was eventually vindicated; the universe is indeed heliocentric. It’s only a matter of time Mr Bernanke.

ISM Manufacturing

The Institute for Supply Management reported their gauge of manufacturing activity accelerated to 55.9 in December from 53.6 the month prior. This marks the fifth-straight month in which the index has remained above 50, the line of demarcation between expansion and contraction. The six-month average is 53.3, a level that some say predicts GDP growth of close to 4% if it holds there for another six months. The question is whether it can hold this level once stimulus spending begins to wane in the 2H 2010.

The internals continue to look good-to-strong in most cases. The new orders index jumped to 65.5 from an already hot 60.3 in November. Backlog orders slipped to 50.0 from 52.0, but remains at that cut line – this is one of those readings we’ve been talking about needs to remain in focus; if it fails to remain in expansion territory for an extended period it will signal current factory workers are not stretched and thus there will be no need to hire additional workers. Supplier deliveries, another gauge of resources becoming stretched, accelerated to 56.6 from 55.7. The employment index rose to 52.0 from 50.8, now three months above 50.

The worse aspects of the report were the inventory gauge, prices paid and eroding breadth.

The inventory reading remains negative. It rose in December, but only from a depressed reading of 41.3 and the 43.4 print for December does not show business confidence has improved much – the six-month average is 40.3. One shouldn’t expect this reading to blow through 50 but until it moves to the high 40s it will signal a lack of business confidence. (When firms become confident they will happily boost inventory levels.)

The prices paid index moved to 61.5 from 55.0; the six-month average is 60.8 – this will put pressure on profit margins and thus force managers to stretch existing work loads more than would otherwise be the case.

Lastly, I can’t help but notice that among the 18 industries that ISM tracks, the number reporting growth has declined for two months – down to 12 from 13 in November and down to 9 from 12 in this latest report for December.

Construction Spending

The Commerce Department showed that construction spending fell for a seventh-straight month in November, down 0.6% for the month. Private-sector residential construction fell 1.6% for the month and the commercial side was down 0.2%. Public-sector spending was of little help for the month as federal and state spending on commercial projects slipped 0.4% -- public-sector residential construction rose 1.2% in November, but this is segments accounts for just 1% of the total number. (For clarity, private-sector residential spending accounts for 30% of all construction spending; private and public commercial outlays makes up roughly 69% of the total number -- 35% from the private sector and 34% from the government.)

Many have counted on residential construction to contribute nicely to fourth-quarter GDP based on a 4.5% jump from the private sector in October. These latest results reduce that good start to the quarter. The housing starts data for November suggest a good reading for December, but with the weather we’ve run into it doesn’t look like this will come to fruition.

Have a great day!

Brent Vondera, Senior Analyst

Monday, January 4, 2010

December 2009 Recap

The Santa Claus Rally helped equity markets advance in December as did better-than-expected economic data and news that major recipients of TARP (Bank of America, Citigroup, Wells Fargo) will be able to repay the government.

The U.S. dollar made a drastic reversal early in the month on signs of improving economic data, most notably an encouraging November nonfarm payrolls report, which gave credence to the idea that the Fed will raise interest rates sooner than the market expects. The stronger dollar sent commodities, especially gold, lower. Meanwhile, the tight negative correlation between stocks and the dollar over the past several months seemingly weakened.

Riskier, or more volatile, asset classes made the biggest gains during the month. Both mid caps (represented by the S&P 400) and small caps (represented by the Russell 2000) outperformed of large caps (represented by the S&P 500) in December and all of 2009. After dominating all other asset classes in 2009, emerging markets continued to outpace large cap stocks in both domestic and foreign developed countries.

It should be little surprise that Information Technology and Consumer Discretionary were among the top performing sectors in December. The other top performing were Utilities and Telecommunication, which both benefited from investors seeking dividends amid low (virtually zero) yields on money-market funds and CDs.

The worst performing sector was Financials. Mega-banks repaying TARP funds is a reason for optimism indeed. But banks pressured prices by flooding the markets with new equity issuances to replace TARP capital. Also weighing on financials was the prospect of the Fed raising interest rates. Financials have greatly benefited from easy profits made by borrowing virtually interest-free capital and buying Treasurys to earn a risk-free rate.

Bonds finished the year with their worst month since October of 2008. The Barclays Aggregate Bond Index declined 1.88 percent in December. Treasurys took the brunt of the damage as heavy supply overwhelmed short-staffed trading desks that struggled to take bonds down. IEF was down 4.39 percent in December and 6.60 percent for the year. Credit and MBS outperformed Treasurys for the month, as did TIPS, which returned -2.09 percent.

--

Peter J. Lazaroff, Investment Analyst
Cliff J. Reynolds Jr., Investment Analyst

Fixed Income Weekly

Risky assets, including stocks and corporate bonds, experienced a substantial recovery in 2009. The same investors who flocked to Treasurys at the height of the credit crisis in 2008, shunned them for riskier investments as the panic subsided. The Fed kept policy ultra-loose throughout the year and kept rates very low, buying $1.086 trillion in Agency MBS and $300 billion in Treasurys through their quantitative easing programs.

A graph of where we stand rate wise. (intraday 12/31/09)


Treasury Issuance
Heavy supply concerns dominated much of my commentary during 2009, but supply actually had very little effect on the rate environment. The Treasury auctioned just under $2.2 trillion in coupon Treasurys in 2009 ($2,195,836,163,400 to be exact). That was a 113% increase from the year before and growth is showing no sign of stopping in 2010. Claims that the US will soon be replaced as the world’s reserve currency were also prominent this past year, causing many to think that the abundance of foreign buyers of US debt will soon be a thing of the past. But the US relies on foreign buyers of debt no more than those same countries rely on the strength of the Dollar to support their export dominated economies. So don’t expect radical changes to the landscape any time soon.

Credit
Investment grade credit was outdone only by non-investment grade credit in 2009. CSJ (1-3 year credit) outperformed LQD (12 year credit) on a price only basis due to rates moving higher, but LQD barely beat out CSJ when you factor in interest income. For 2009 CSJ was up 3.09% price only and 7.08% total, while LQD was up 2.46% and 8.46% respectively. They both massively underperformed HYG (High Yield Corporate Bond) which returned 28.5% in 2009.

This year’s strong rally in credit was still only a partial reversal of damage done in 2008. By most measures credit spreads are sill wider than they were before the crisis began, but absolute yields are still lower, which is very accommodative to corporations looking to borrow.

Credit Default Swaps, which are used as insurance against a default, followed the rally in corporate bonds in 2009. According to Markit the cost of default protection on a broad basket of corporate debt fell 63% in 2009 to 85 basis points. The cost is quoted as an annual payment based on a percentage of the the notional amount insured.


2010?
So what’s in store for bonds in the New Year? The Fed still has about $200 billion in MBS to purchase, which should be completed by March. Expectations for Treasury issuance in 2010 vary from “as much as humanly possible” to “even more than that”, and rates are likely to edge higher throughout the year as the fed begins to signal a policy reversal in the second half of 2009. Fannie and Freddie are all but entirely owned and run by the Government, so subsidies to homeowners will likely continue even after the tax credit expires at the end of April and the credit quality of their bonds will likely continue to move closer to that of Ginnie Mae. And based on Bernanke’s demeanor and the Fed’s recent language my expectation is for them to move more than 25 basis points on the Fed Funds Target rate (to .75% maybe?) by Q3 2009 (at their September 21st meeting maybe?) after removing the remainder of their emergency liquidity and repo programs by the summer.

Happy New Year Everybody!!

Cliff J. Reynolds Jr., Investment Analyst

Daily Insight

U.S. stocks went out on a bad note, apropos for the decade, as a second-straight weekly decline in initial jobless claims failed to inspire a rally. Treasury prices fell, moving the 10-year yield to the top-end of its six-month range (3.85%), and the price of oil inched closer to the $80 handle after sliding to $70 just two weeks back.

Activity was in super-sloth mode as less than 650 million shares traded on the NYSE Composite – about one-third less than what’s become normal on the last session of the year.

And speaking of the year that was quite a turnaround from the March lows. The broad market began the year lower by 25% just 46 sessions into 2009, but staged a dramatic comeback, jumping 67.4% from that point to recoup nearly 50% of the losses from the October 9, 2007 peak.

For the decade, the S&P 500 declined 24.10% in simple-price terms (down 2.71% annualized) and lower by 9.10% when including reinvested dividends (down 0.94% annually). On an inflation-adjusted basis, the decade in stockland was worse with the annual decline at roughly 3.5%, but this is just in terms of price and does not include the contribution from dividends. And worse still for the international investor as the dollar got clocked by 22.25%. (When the foreign investor converts back to his/her home currency, they received less of that currency.)

But what’s done is done, let’s look to the future. The multiple compression (decline in the market P/E) that’s occurred over the past several years makes the chances of strong returns for the new decade all the more likely. Of course, this is not axiomatic. For strong returns to materialize we must have sound monetary policy and a tax policy that incentives entrepreneurial endeavors, the investment that those upstarts need, and work over leisure. (We must also get much more serious about security.) The wrong policies will lead to another rough 10-year stretch, just ask the Japanese.

All was not totally lost over the past 10 years, a well-balanced portfolio that encompasses an array of asset classes helped. For instance, mid cap stocks rose 63.42% during the decade (up 5.03% annualized); small cap stocks added 23.90% (up 2.16% annualized). Reinvesting dividends into these indexes produced a 6.35% annual return for the mids and 3.55% per year for smalls. The main emerging market index was up 7.29% annually and bonds were obviously positive.

The CRB, which tracks a basket of commodity prices, rose 38.14% for the decade – most of the return was made by 2004. It’s been an especially wild ride for commodity prices since 2004 as the index was up as much as 130% since 1999 at one point during the summer of 2008 and flat for the decade as of February 2009. The CRB index was driven by copper (up 290%), gold (up 278%), and oil (up 210%).

Home prices, as measured by the median price for an existing home, rose 24% for the decade (up 2.25% annually).

Market Activity for December 31, 2009


Jobless Claims

The Labor Department reported that initial jobless claims continued to fall to that very important 400K level – a level that always signals at least some monthly payroll growth. Initial claims fell 22,000 in the week ended December 26 to 432,000. The four-week average declined 5,500 to 460,250.

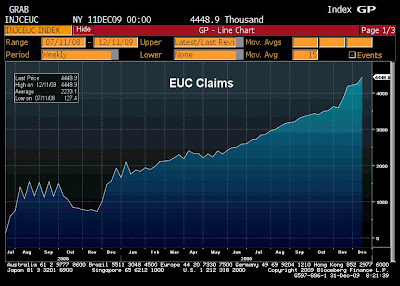
While the initial claims data show the pace of firings has eased greatly, the continuing claims data unfortunately show hiring has yet to take hold. Standard continuing claims (the traditional 26 weeks of benefits) fell 57,000; however, claims for Emergency Unemployment Compensation (EUC) more than offset this as they jumped 191,000. Until EUC halts its trend to new highs, there is no clue that meaningful monthly job growth has begun.


Outlook

Stocks

For 2009, the stock-market trade, at least post-February, was all about easy money and rock-bottom interest rates encouraging a move into risky assets as the hunt for return was on. The 2010 market should depend on profit growth (and it better be accompanied by some top-line improvement or the strong profit growth that will come in 1H 2010, enabled by massive cost-cutting, will peter out); it will take aggressive earnings improvements for stocks to withstand even marginally higher interest rates, if they are to materialize.

The Economy

U.S. corporations are the bright spot for this economy as they have locked in leverage at very low rates and sit on mounds of cash. (The same cannot be said, sorry to say, for households; and the government debt situation is a mess.) However, firms will remain chary with this cash as final demand will struggle to pick up – a function of high unemployment and exacerbated by the $500 billion, at the low-end of the estimate, in additional credit-card lines that will be erased in 2010.

One of the places business caution will continue to show up is in hiring. Yes, we’ll see monthly job growth begin within the next two months (something we first mentioned following the October jobs report), after shedding more than seven million jobs over the previous two years – 4 million gone in a six-month stretch, November 2008-April 2009. But the business side of the economy, and I’m talking in large part, is the only saver right now. Government is going hog wild on deficit spending and households are backing off from their hog-wild escapade of the previous several years. Businesses will also have to manage around what they estimate Washington has in store for them via higher tax rates and regulations.
Remember this: By the spring, hiring for the 2010 census will peak as 800,000 workers are needed for this endeavor, according to the government. This will boost the monthly job gains for a couple of months (showing up via a spike in government jobs) and lead to some euphoria, but shortly thereafter these people will be looking for work again – the census work is a six-week gig.

On banking, the 2010 economy will have to face a gathering pressure from the credit markets as banks will be forced to add to provisions due to still increasing delinquencies. This is simply a reality of the credit bubble that still must be dealt with, affecting the economy for a while still. And more to come as 25% of all mortgages are underwater and 5.3 million borrowers are 20% or more underwater – 2.2 million properties are worth less than half of the mortgage balance, according to First American CoreLogic – that’s really hard to believe but even if they are off by a long shot, you’re talking a real problem. (We must engage in the RTC-style program that TARP was originally sold to do – or let the market take care of it, but there is zero political will for this. The bad assets that still sit on bank balance sheets must be removed; the government can sit on these assets for several years if that is what it takes and sell them off when the time is appropriate. This should have been the main federal government response to this entire situation, that and slashing tax rates. Alas, we dropped that ball. The Bush Administration fumbled it big time and the Obama Administration ran with the darned thing, in the wrong direction.)

Another serious issue is the one that arrives when government intrudes on the private sector to the degree it is at the present. It sets up serious barriers to entry for upstart businesses. Who’s going to create the 100,000 jobs per month that it takes to just keep the unemployment rate from rising – the 300,000 per month it takes to move the jobless rate lower in a reasonable amount of time? (Maybe those numbers need to be even greater as a higher number of workers in their early 60s come to the cruel reality that they cannot retire yet due to the $10 trillion reduction in household net worth that’s occurred from the peak, making it more difficult for newer entrants into the job market.)

Why do you think that many of the CEOs of the largest U.S. corporations haven’t a problem with this government largess? They don’t because they have the resources to buy themselves handouts and government contracts, making it easier to manage around increased regulations and taxation – the government is picking winners and losers and some of the largest corporations are buying themselves into the winner’s circle. The smalls don’t have a chance in this environment and the big guys know it; they know it shuts out current and future competition. This is a problem that must be reversed. Small business currently accounts for 65% of job growth, get in the way of this engine and you get more crazy policies out of Washington as politicians scurry for anything that they believe will get them re-elected as the unemployment rate remains high. When Washington is this involved do not underestimate their ability to screw things up, royally.

The U.S. economy will emerge from this situation, but I fear the timeline has been delayed due to the government’s response. That response may very well have eased the degree of downward economic pressure, but always elongates the cycle to a full-fledged recovery. Sure, GDP will record 3-4 quarters of growth, with a couple of these being above-average results as the inventory dynamic adds 1.5 -2.0 percentage points to growth and government infrastructure spending peaks in 1H2010, which may add another percentage point. There may even be a 6% GDP quarter in the cards, possibly in Q2, as those refundable tax credits for first-time homebuyers are collected and propel consumer spending. Enjoy it while it lasts as 2H2010 may very well show the rebound to be especially transitory. Expect something in the manner of 3.0%-3.5% GDP for all of 2010, almost all based on stimulus and a transitory inventory rebuild.

I hear economists talking about how strong 2010 is going to be. You’ve heard it plenty of times now: “The deeper the contraction, the stronger the upswing.” For this to result, we’ll have to see 7.75% GDP growth for the entire year in order to compare with past rebounds from the worst recessions of the postwar era – doubt that’s in the cards. One reason for the doubt is that I’m mindful past postwar-era recessions were simply driven by the inventory cycle. That is, as manufacturing stockpiles became bloated the economy had to wait for the next production surge as those inventories needed to be sold off first. But those past recoveries had the luxury of relying on an expansion of credit to offset the organic weakness. Not this time; no such luxury – households don’t have the capacity with the household debt/disposable income ratio at 123%. Notice in the chart below that with each recovery during the past 30 years the household debt/income ratio kept rising, spiking to the insane level of 130% as the Fed induced such behavior with its very low interest-rate environment 2002-2005.

Besides, let’s be serious about how we define a strong expansion, we’re talking about business cycles here. You’ll hear most of the optimists effuse positively about 2010, but express concern over 2011. The average business-cycle expansion over the past quarter century has lasted roughly eight years on average. One year of growth is not an expansion; more frequent downturns is not a positive development. It will take a significantly higher than average growth rate for a prolonged period to bring back the jobs that have been extinguished over the previous two years. Without a durable recovery, the household-debt pay down process will take longer to play out.

I guess an outlook would be remiss to not even mention geopolitical concerns. I’ve spent so much time on this subject over the past few years, I’ll keep this topic short. At some time, and the clock is ticking, someone will have to deal with Iran’s hell-bent desire to weaponize nukes. If the Revolutionary Guard doesn’t put down their guns and stop shooting student protesters (which there is a chance of this happening, just remote), or the U.S. doesn’t take out/seriously delay the regime’s nuclear capability, then Israel will do it. Beyond thinking about its survival, Israel also must worry about capital flows to the country. If investors believe that Iran is two years from a bomb, they won’t wait to pull capital from Israel until that date arrives, they’ll do it much sooner. Israel will be forced to act for a number of reasons.

So there are a lot of headwinds out there, but assuming a geopolitical event or large-scale domestic terrorist attack does not occur, we should get a short-lived bounce in economic growth. While things may very well take longer to return to normal, we will get past this trouble. When the Fed normalizes interest rates (either voluntarily or by force via the bond market) this will drive the final leg of the de-leveraging process. That is when a durable economic expansion will emerge from the next downturn – the kind of expansion that we’ve become accustomed to; the kind of expansion that this great country is capable of producing. A durable economic expansion will emerge in time, but it is likely to take an extended period.

One year closer to normalcy, as Truman would have put it.


Have a great day!


Brent Vondera, Senior Analyst
Thursday, December 31, 2009

Daily Insight

The S&P 500 made a run for positive territory several times yesterday but to no avail, until the final push of the session moved the broad market fractionally to the plus side; the Dow and NASDAQ Composite managed slightly more substantial gains.

A strong manufacturing report out of the Chicago region appeared to do more harm than good as it led to some speculation the Fed will withdraw stimulus measures sooner than previously believed. I don’t know how many times Bernanke & Co. have to explicitly state that they’ll keep monetary policy floored for a while still, but we remain in this what’s-bad-is-good environment (bad is good because it means the easy money trade rolls on) so I guess the reaction, stocks struggling to move higher on a strong report, shouldn’t be terribly surprising.

Tech was the leading sector on the session; consumer discretionary shares the worst performing group. The 10 major sectors were spilt, with five in the green and five in the red.

The seven-year Treasury auction was well–received, as the rise in yields of late seemed to support this week’s $118 billion in debt sales.

We’ve got one session left before getting this decade in the market behind us. The S&P 500 has fallen 23% since the end of 1999 (that’s on a simple-price basis, not including dividends), the first decline for a decade since 1930-1939. Including dividends, the index lost roughly 10% since 1999 (0.9% per year), the first negative annualized return over a 10-year stretch in the index’s history, which goes back to 1927, according to S&P’s Howard Silverblatt.

Market Activity for December 30, 2009
Chicago Purchasing Managers Index

The Chicago PMI (a gauge of manufacturing activity from the nation’s largest factory region) jumped to 60.0 in December, the highest level in nearly four years, from 56.1 in November. The reading easily surpassed expectations, which had the figure slipping to 55.1. The Chicago region is the main factory corridor for the auto sector, so vehicle assemblies to restore what have been low inventory levels for this segment of manufacturing was likely the catalyst. Chicago does involve a good level of electronic-goods production also, the holiday shopping season surely played a supporting role as well.

Nearly all of the sub-indices of the report looked really good, The new orders index remained hot, hitting 63.5 (highest level since May 2007) after 62.8 in November; order backlogs entered expansion mode for the first time since August 2008, hitting 53.0 after 46.5 in the previous month – this is an important gauge to watch, if it remains above 50 for several months it’s one signal current workers are getting stretched and new hires will be necessary; the employment figure jumped to 51.2 from 41.9, the first move into expansion since November 2007; and supplier deliveries remained at a good level, slipping but just slightly to 56.2 from 57.4 in November – this is another key gauge as a sustained stay above 50 will also signal workers are stretched by new orders.

Unfortunately, the inventory reading remained in contraction mode, but it improved and that is all it takes to offer a boost to GDP. The reading rose to 39.4 from 34.9 – this is a depressed level, remaining below the average since the recession officially began (40.3) and below the average for the decade of 45.9.

So, we now have two of the major regional factory gauges that have posted strong results (Chicago and Philly) for the month of December, while two have shown deterioration (New York and Richmond). Now we wait for the nationwide look at manufacturing via the ISM data, which arrives on Monday. The market expects a reading of 54, which would be good. Chicago is predicting something more, but it hasn’t been the best indicator of late – normally it is an excellent signal for what’s to come from ISM.

Ticking

Last week, I think it was, we talked about the trouble brewing within the Chinese real estate market. Over the past 12 months apartments in Beijing have more than doubled in price and speculators have driven the high-end market up by 55% in the nine months ended September in Shanghai; housing starts have nearly tripled over the past 12 months.

It will be interesting to watch when exactly the Chinese banking bomb blows, they’ve had problem loans on their books for a while but nothing like the problems that arise when their real estate bubble pops. The escalation in Chinese RE prices appears to dwarf what occurred here in the U.S.

One indicator of economies becoming overheated, not a great one for those serious about this issue but interesting nonetheless, is the Skyscraper Index put together by Andrew Lawrence of Dresdner Kleinwort (it follows through on the Skyscraper Indicator, created by Ralph Elliot in the 1930s). The index holds that the impulse to build the world’s tallest structures is a strong indication that an economy is about to run into deep trouble. As Lawrence states, the planning for the Singer and Met Life buildings foretold the Panic of 1907; the Chrysler and Empire State buildings, the Great Depression; the Petronas Tower in Malaysia, the Asian Crisis. The tallest building in the world at the present is the Burj…in Dubai.

Next on the list? The Shanghai Tower, currently under construction. Heads up!


Have a great day and Happy New Year!


Brent Vondera, Senior Analyst

Wednesday, December 30, 2009

PEG ratio

The P/E ratio (or price-to-earnings ratio) is one of the most well-known valuation tools, but some people neglect to consider the impact of future earnings growth on this ratio.

The price/earnings-to-growth ratio (or PEG ratio), provides a forward-looking perspective and allows investors to compare the relative attractiveness of a stock in the context of the firm’s earnings growth outlook. Similarly to the P/E ratio, a lower PEG ratio means that the stock is more undervalued.

Calculating the PEG ratio is quite simple – divide the P/E ratio by the three- or five-year earnings compound annual growth rate. To better understand how to use the PEG ratio, consider these two technology firms.

  • Hewlett-Packard (HPQ) has a P/E ratio of 13.82 and a growth rate of 11.8%
  • Apple (AAPL) has a P/E ratio of 33.70 and a growth rate of 18.8%

Hewlett-Packard is clearly the cheaper company based on P/E ratio alone, but an investor might argue that Apple’s high P/E is justified by its superior growth. Apple has gained a reputation for introducing cutting-edge products and, accordingly, Apple is projected to grow earnings at an annual rate of 18.8%. Hewlett-Packard, on the other hand, is projected to grow earnings at 11.8% rate.

But after calculating both firm’s PEG ratios (Hewlett-Packard is 1.17 and Apple is 1.79) we discover that that Apple’s growth rate, although higher than Hewlett-Packard, does not justify its higher P/E. In other words, Hewlett-Packard’s stock is a better value (even if Apple makes better computers).

As you can see, the PEG ratio is useful for determining whether a firm’s high growth potential justifies their valuation.


--

Peter J. Lazaroff, Investment Analyst

Daily Insight

U.S. stocks bounced between gain and loss on several occasions yesterday, but unlike Monday when a late session move higher delivered the broad market to the upside a move lower in the final minutes ended a six-day winning streak. Overall, the beginning of this holiday-shortened week has turned out as uneventful as maybe it was expected to as the last two sessions canceled one another out.

The day’s economic data was really not enough to push stocks higher. The latest housing report showed prices rise month-over-month in October, but it was a negligible gain and too many cities continued to show no durable recovery in prices is yet upon us. The latest consumer confidence reading showed a nice improvement in households’ expectation of the future, but even that reading remains quite depressed and if jobs growth fails to get rolling in substantial fashion a few months down the road, even expectations may get smacked down again. The present conditions index of the report made a new cycle low.

Really the only excitement yesterday was the ubiquitous internet photos of the “Great Balls of Fire” underwear, the clandestine means for the failed explosive device via al Qaeda’s latest human mule.

Seven of the 10 major S&P 500 industry groups closed lower on the session, led by energy and financial shares. The three sectors that gained ground were led by consumer discretionary and industrial shares – consumer-staples being the third of those sectors ending in the black.

The $42 billion five-year Treasury auction went well as the yield was 1.4 basis points lower than the when-issued were trading prior to the auction. The bid-to-cover (gauge of demand) was 2.59, lower than the previous two auctions, but in line with the four-auction average. The indirect bid (gauge of foreign buying) was the worst aspect of the auction, coming in at 44%, down from 60.9% in November and below the 54.2% of the past four auctions. Today’s seven-year auction will be the test for the week.

Market Activity for December 29, 2009
S&P CaseShiller Home Price Index


The CaseShiller HPI (which tracks home prices for the 20-largest metro areas) extended its streak to five months as the measure showed October prices advance 0.37% from the prior month. From a year-over-year perspective, the improvement extended for a seventh month – relative to October 2008 prices were off by 7.28%, which follows a 9.27% decline in September (from the year-ago period).

Nine of the 20 cities tracked registered price declines for October, the same number as last month. Tampa led the declines, where prices were down 1.19% for the month, followed by Chicago (down 0.98%), Miami (down 0.48%), Cleveland (down 0.40%), Las Vegas (off by 0.28% and has never shown an increase since the market collapsed); Boston, NY, Atlanta and Dallas also registered price declines.

For the 11 cities that gained ground, San Francisco led the way (up 1.73%), followed by Detroit (up 1.23%), San Diego (up 1.11%), LA (up 0.69%). Seattle, Portland, Denver, Minneapolis and Washington DC and Charlotte rounded out the positive contributors.

Since hitting its cycle low in May, the CaseShiller HPI has rebounded 3.4%. The current level was first hit in September 2003. Peak-to-date, CaseShiller has home prices down 29.55% -- April 2006 was when prices peaked, according to this index.


Consumer Confidence

The Conference Board’s consumer confidence reading for December improved to 52.9 from an upwardly revised 50.6 (previously reported at 49.5) for November – basically in line with the expectation of 53.0. For perspective, the long-term average is 94.1. The reading averaged 103.4 in 2007 and 60.5 in 2008.

The increase was driven by a nice move within the expectations index (consumer’s view of things six months out), which rose to 75.6 from 70.3. That’s the highest since the recession officially began in December 2007. The cycle low, which is also the all-time low, of 27.3 was touched in February.

The present situation index weighed on the headline reading, slipping to 18.8 (a new cycle low, the all-time low of 15.8 was hit in December 1982) from 21.2 in November. With the present number falling, we’ll have to see a marked pick up in economic activity, and thus job growth, or that expectations number is going to get hammered again.

As we explain each month, the most important reading is the jobs “plentiful” less jobs “hard to get” reading. This is the confidence index’s best indication of future consumer activity trends. The measure made a new cycle low of -46.6 in November, but improved ever-so-slightly in December to -45.7. The all-time low is -58.7, hit in December 1982.

The share of respondents stating jobs are “plentiful” fell to 2.9 from 3.1 in the previous month, but those stating jobs are “hard to get” improved to 48.5 from 49.2, more than offsetting the decline in the plentiful reading.

The readings on plans to buy a car or a home six months out continued to decline. Plans to buy a car fell to 3.8 from 4.5 and the plans to buy a home hit a new 27-year low, falling to 1.9 from 2.1.

Subsidize It

The Treasury Department will throw another $3.5 billion GMAC’s way so that the financial-services firm can keep their mortgage arm, ResCap, out of bankruptcy as loan losses continue to mount. This is on top of the $12.5 billion Treasury has already thrown down this rat hole. We likely haven’t seen the extent of this bailout story as GMAC’s loan portfolio will record additional losses down the road – what’s going to happen when home prices slip just another 5% over the next 6-12 months? With the way that banks have delayed the foreclosure process, there’s little doubt these distressed properties will add significantly to home supply.

The government will hand the 90-year old lender all the money they need to cover losses as the auto market can’t afford GMAC going down, or even slow their financing activity.


Have a great day!


Brent Vondera, Senior Analyst

Tuesday, December 29, 2009

Daily Insight

U.S. stocks bounced around the flat line for most of the session, ending in positive territory thanks to a tick higher in the final minutes. The gain extended the broad-market’s winning steak to six sessions. We didn’t have a major economic release to trade on, and with most traders out until next week it was overall a quite session.

This time of year is almost always subdued, although things can get interesting on occasion due to the lack of volume; the market can become especially news-driven when there is an event with which to trade on. Thankfully, the failed act of terrorism, the targeting of civilians by an enemy combatant, didn’t offer such a scenario. (But I’ve got to say, and long-time readers know that I’ve been very concerned about our security efforts for a long time, when you have someone go from Nigeria to Amsterdam to the U.S. without luggage -- and on top of that our unwillingness of inability to revoke the visa even after his own father warned that his son may have been radicalized -- we don’t seem terribly serious about this problem; a problem that will grow over time if not properly checked. When one thinks about risk-management within the investment world, this issue has been and must remain a serious element of that risk assessment.)

Telecom shares, the worst-performing sector for the year, led the advance. In fact, all seven of the 10 major industry groups that rose on the session outperformed the broad market. The three that failed to close in positive territory were consumer discretionary, financials and industrials – ranked 3, 4 and 5 in terms of 2009 performance

The $44 billion Treasury auction went fine, not as well as previous auctions but ok. The rate was pushed higher, 1.089% (what a wonderful yield for two years) compared with the 1.077% at which the when-issued was trading just ahead of the auction. The bid-to-cover ratio (measure of demand) came in at 2.91, the previous auction had a bid-to-cover of 3.16 and the four-auction average is 3.07. The indirect bidding (foreign buyers, including central banks) came in at 35%; it had averaged 43% over the past four auctions. In general though, no big deal. Tomorrow’s $32 billion seven-year auction should be the tougher test, but we shouldn’t run into too much trouble, not yet at least. If inflation concerns arise, or the bond market begins to believe that this expansion is for real, that’s when the market will fully shun these levels of interest rates and trouble in financings this deficit spending may begin.

Market Activity for December 28, 2009
Holiday Sales

MasterCard Advisors’ SpendingPulse has holiday sales up 3.6% from the year-ago period – their definition of the shopping season is the timeline Thanksgiving-Christmas, others extend it out to year end. This look by MasterCard does include food and health-care expenditures, which means there is some H1N1 vaccine in the number. There was also an extra shopping day this year (28 days between Thanksgiving and Christmas vs. last year’s 27), adjust for that and sales rose 1%. Severe winter weather across most of the country also helped to boost sales – while many concentrated on how this event hurt in-store traffic, it surely boosted online sales of winter apparel enough to offset the physical-store weakness.

According to SpendingPulse, E-Commerce sales are up 15.5% since Black Friday (day after Thanksgiving), relative to the year-ago period; electronics sales are up 5.9%; jewelry sales higher by 5.6%; footwear up 5.0%; luxury (ex. jewelry) is up 0.8%; apparel down 0.4% and department stores down 2.3% -- again, clearly this is a function of online activity stealing some sales due to the weather. Last year’s holiday shopping season was the worst since 1970, according to the International Council of Shopping Centers.

The final week of the year is also an important one as it accounts for roughly 15% of total holiday sales, according to Dana Telsey of Telsey Advisory Group.

China Watches Inflation, But It’s Just Talk for Now

Chinese Premier Wen Jiabao, in a rare interview, discussed inflation risks over the weekend – pointing to a surge in real estate prices and credit expansion (doubling over the past year as virtually every other economy shows credit is contracting). Wen stated that the Chinese government will address the issue before it becomes a problem. That’s what everyone always thinks, but it is too late by the time politicians begin to address it, at which point the measures necessary to ultimately tamp harmful levels of inflation are intensely detrimental.

We’ll watch for the Chinese to clamp down on credit by tightening standards. For now, they explicitly state that aggressive stimulus measures will remain in place, which propelled the Shanghai Exchange and other Asian markets over the past two sessions.

The Chinese leader also expressed that they will not cede to foreign pressure and allow their currency to appreciate – meaning they will not remove the peg to the U.S. dollar. So much for Mr. Mandarin himself (Tim Geithner) going over to China last month to smooth over the Chinese – nice try. Maybe they allow the currency to float for other reasons, but by explicitly stating that foreign governments’ calls to do so will have no bearing on their decision-making process Wen makes quite the public political statement.

Government Still Can’t Pull Back, But Will Have to Eventually

The Treasury Department has removed a $200 billion limit on aid to Fannie and Freddie and promised to cover their losses through 2012. So, just as the Federal Reserve plans to end it purchases of mortgage-backed securities by the close of first-quarter 2010, Treasury will be their to pick up the slack. Washington is extremely concerned that higher mortgage rates will result when the Fed exits from their purchase program, and the damage this will do to a housing market that has become conditioned to sub-5.00% rates, as well they should be.

The two government agencies underwrite nine out of every 10 new residential mortgages, twice the level prior to the crisis. The housing market may still be in decline if not for the government backing, but such actions carry their own risks. You can’t attempt to backstop everything, sometimes you just have to let the market find the bottom. Increased government involvement has done more harm within the labor market than may have otherwise been the case. Firms know what follows this level of deficit spending – higher tax rates.

As Lender Processing Services (a major provider of mortgage data) has been explaining for a while now, the mortgage delinquency problem is moving upstream. The level of deteriorating loans with credit scores above 680 are making up a larger percentage of all defaults. It’s no longer about sub-prime, but the traditional drag on housing (high unemployment) is now becoming a larger problem for the market. Of the loans that were current at the end of the prior year but now 60 days-plus delinquent as of September of the following year, > 680 FICO mortgages made up 40% of that number (750,000 of the 1.831 million loans). This is up from 35% in the prior year

It seems that the cost of this government support is going to be very costly. It masks the problems in the short term, but they will become evident over time.

Week’s Data

We were without a major data release Monday, but get back to it this morning with the S&P CaseShiller Home Price Index (October) and the Conference Board’s consumer confidence reading (December). CaseShiller is always a heavily watched release; we’ll see if the index can manage a fifth-straight monthly increase and continued improvement on the y/o/y figure, expected to be down 7.15% after September y/o/y decline of 9.36%. The confidence reading is expected to improve to 53.0 for December from 49.5 in the prior month. The figure needs to break above a reading of 60 in order to move past recessionary levels – the 40-year average is 95.8.

On Wednesday we get the Chicago Purchasing Manager Index, the gauge of factory activity out of the largest manufacturing region. The number is expected to slip from November’s reading, but remain in expansion mode nonetheless. It will need to meet expectations as two of the three regionals we’ve gotten for the month thus far have not been good.

We’ll round it out on Thursday with the weekly jobless claims data. The figure is expected to hover around the 450K level, and it should. The problem for claims at this point is the continuing numbers, which continue to rise.

Other Notes

Today marks 20 years since the Nikkei 225 (Japan’s main stock exchange) hit its all-time high of 38,915. Currently that bourse resides at 10,638. This is what can happen when an economy, still the world’s second-largest but probably not for long, implements terrible policy for an extended period of time. For sure Japan has structural issues, namely birthrates that are close to non-existent – not even close to replacement levels. But strong economic and monetary policy would have sparked economic growth, jobs, and encouraged immigration, thus easing or even completely offsetting the population problem.

GM is offering Saturn and Pontiac dealers $7,000 to clear these closed-out models from inventory. This will certainly boost December auto sales but is nothing more than another round of front-loading sales. Just as the clunker-cash program stole sales from the future, this program – although necessary to get discontinued models out the door – will do the same.


Have a great day!


Brent Vondera, Senior Analyst

Monday, December 28, 2009

Stock performance following a bad decade

The new year is approaching and soon investors will be scouring over year-end performance reports. Sadly, one of the most common mistakes investors will make is using past performance as the basis for their investment decisions.

Those that harp on past performance may find it difficult to invest in equities following a decade that was plagued by two brutal bear markets. But shunning equities may be a mistake.

Consider the table below.


Each time the average ten-year return of the S&P 500 was below 6%, the following ten-year period has been very good to investors, with an average return of 13.14%. The following 20-year period is even more impressive, averaging 14.82% per year.

There are no guarantees this trend will continue going forward. After all, it’s impossible to consistently predict the direction of the market (see my June 30, 2009 post: Are you chasing performance?).

Still, the table above should at least make you rethink shunning equities for emotional reasons.

--

Peter J. Lazaroff, Investment Analyst

Daily Insight

U.S. stocks added to a nice holiday-shortened week (S&P 500 gained 2%) as traders were determined to push the indices higher. Thursday’s economic releases were certainly a help as initial jobless claims fell more than expected and durable goods orders, excluding transportation, also came in much better than was anticipated.

Information technology shares led the broad market higher, with financials and basic material shares also posting market-beating gains.

Volume was about as flat as it gets with just 300 million shares traded. It was a half-day session and thus expected for activity to be light, but this Christmas Eve was about 50% lighter than what we’ve seen over the previous four years.

Interest rates continued their march higher on Thursday, particularly on the long-end as the 10-year Treasury is now yielding 3.80% (spiking from 3.20% as of November 30) – up another 4 bps to 3.84% this morning. We’ll get another $118 billion in government debt auctions this week ($1.4 trillion for all of 2009) so we’ll see how they go, and the direction that rates take.

Market Activity for December 24, 2009
Jobless Claims

The Labor Department showed that initial jobless claims fell 28,000 (a 10,000 claim decline was expected) to 452,000 in the week ended December 19 – nice to see initials back to the 450K level after bouncing back to 480K over the previous two readings. Initial claims are now back to the level of September 2008. The four-week average (chart below) of initial claims fell 2,750 to 465,250.

Continuing claims also fell, down a meaningful 127,000 to 5.08 million -- that is for the standard 26 weeks of benefits. However, claims for EUC (Emergency Unemployment Compensation), which kicks in to provide up to another 73 weeks of benefits, added another 142,000. So, again, this suggests that the decline in standard continuing claims is more a function of those benefits running out rather than a resurgence in job growth. (That said, as I’ve been mentioning since the October jobs report was released, we should begin to see some job growth arise over the next couple of months, it’s just that the increase is likely to be quite mild.)


Until we see EUC begin to trend lower, or at least halt it’s consecutive-week increase, the evidence is just not there that statistically significant job growth will take place anytime soon. And frankly it is unreasonable to expect this to occur just yet. These things take time to materialize even during a normal expansion, which this is not. This time we must contend with very low capacity/resource utilization rates. Therefore, those resources have a longer distance with which to be stretched, if you will, before firms begin to aggressively add to payrolls – average hours worked per week continues to hover near the all-time low and until these hours pick up for existing workers, should one expect much by way of new hires?

Durable Goods Orders

The Commerce Department reported that durable goods orders rose just 0.2% in November (+0.5% was expected), but this seemingly weak headline reading off of a 0.6% decline for October was affected by a large drop in commercial aircraft orders. The report was actually well-balanced and quite strong.

Excluding transportation orders, and thus removing the 32.6% decline in the commercial aircraft segment, durable goods orders jumped 2.0% (nicely outpacing the expectation for a 1.1% increase), which follows a 0.7% decline in October. Total orders are down 6.0% on a year-over-year basis and ex-trans are down 4.9%.

Overall transportation orders fell 5.5% -- vehicle and parts orders declined 0.2% and, again, nondefense aircraft plunged 32.6% after a 39.3% jump in October. The rest of the report looked really good though. Computers, electronics orders rose 3.7%; electrical equipment orders increased 3.2%; machinery orders rose 3.5% (following a large decline of 7% in October).

Those components of the report pushed non-defense capital goods ex-aircraft higher by 2.9% after a 2.0% drop in October. This is the reading we like to watch most closely as it is the proxy for business-equipment spending. This segment is down 8.9% y/o/y, but the last three months have been positive, up 5.5% at an annualized rate.

We need to see this segment, as I’ve been saying for a while now, trend higher; this economy desperately needs help from the business side. One hopes for this to occur, but U.S. corporations appear to be managing capital expenditures to maintenance levels as they manage around lower sales. This will help profits in the short term but will not be helpful for overall economic activity if this process extends for a while – it will keep final demand depressed; business-equipment spending is a huge job creator.

The inventories segment of the report showed that firms continue to reduce stockpiles, which is quite strange based upon the record pace of liquidation of the previous few quarters. The largest inventory liquidation on record occurred in the second quarter, and the third-quarter liquidation only looked good compared to that historic reduction – firms remain abnormally cautious. Durable goods inventories fell 0.2% in November, but the three-month annualized change is half that of the prior month – and that is all it takes to boost GDP. We are still waiting for actual re-stocking to begin, but firms continue to hold off.

Expectations for the fourth-quarter GDP reading are definitely going to be boosted by this report. Shipments of durable goods, which gets plugged into GDP, rose 0.3% following a 0.7% rise in October. That’s a great start to the quarter and will help to offset what may be a drag from the housing component. Housing construction was up in November, but on a quarter-over-quarter basis is down. If the December housing starts reading (which we’ll get in three weeks) falls, this segment won’t contribute to GDP.

Reminded, Yet Again

Everyone probably expected the health-care debate to dominate the Washington storyline for a while, but a little event on Christmas reminded (or re-reminded) us that something else looms larger – no matter how badly we’d like to ignore it, there are people, organizations and regimes that want to do us grave harm. Thankfully, the terrorist’s device failed, buy they’ll keep coming; their desires are surely not contained to taking down airplanes, but much more. As I have written for the last eight years, security is key. Obviously now, we have major economically endogenous issues to also deal with but if we don’t get security right, and the overall policies that greatly diminish the chance of major attack, it makes it that much harder for a normal business cycle expansion to take hold.

Futures are higher this morning. Quite the opposite would be the case if it were that explosive device, rather than the terrorist’s leg, that had ignited.


Have a great day!


Brent Vondera, Senior Analyst

Thursday, December 24, 2009

Daily Insight

U.S. stocks shook off two ugly housing reports to extend the recent winning streak to four sessions. A good headline personal income number helped traders look past the housing data. Even though the income figures are being propelled by government transfer payments, which can only be transitory in nature, the wage and salary component did register a nice increase and that offered stocks a little boost. Money was most focused toward mid and small capitalization indices as the broad large-cap market was only slightly higher.

Basic material, tech and energy shares led the advance. Financials were the worst-performing sector; health-care stocks slipped also as these were the only sectors of the major 10 that closed in negative territory.

Volume was extremely weak, which is always the case for the session prior to Christmas Eve, but even more so than is typical as just 740 million shares traded on the Big Board – something closer to 900 million has been the norm. Today is a holiday-shortened session and most traders are long gone so we’re likely to just go through the motions unless the day’s economic releases (jobless claims and durable goods orders) print readings that are far from expectations.

The U.S. dollar ended a six-day rally.

Market Activity for December 23, 2009
$80 Looks to be Back in Play

Crude-oil for January rose 3% to $76.67/barrel yesterday after the weekly energy report showed supplies fell more than expected. Crude stockpiles slid 4.84 million barrels last week, a fall of 1.6 million was expected, as consumption of gasoline rose 0.9% from the prior week to 9.05 million/day and distillate fuels (diesel and heating oil) rose 5.2% over the previous week – some of this was obviously due to colder weather, especially in the Northeast.

Not all of the decline in stockpiles was a result of increased demand, though it is nice to see gasoline consumption 2% higher than the ultra-weak levels of a year ago. While refinery utilization rose to 80%, this is still rock-bottom as 88% is the long-term average and 83% was viewed as the floor prior to the beating the economy’s taken over the past year. Also, oil imports fell another 0.8% in the latest week to 7.71 million barrels, the lowest level since September 2008 when Hurricanes Gustav and Ike punished the Gulf Coast and shut down the ports.

Mortgage Applications

The Mortgage Bankers Association reported that applications fell 10.7% in the week ended December 18, the first decline in four weeks. Both purchases and refinancing got clocked, down 11.6% on purchases and 10.1% for refis. The 30-year fixed rate mortgage rose to 4.92%.

The rate will move above 5.00% next week as Treasury yields have jumped, which means the Fannie and Freddie commitment rates also rose. Based on those moves the 30-year mortgage rate is going to 5.20% next week. This will be a nice little snapshot to show how housing will react to just marginally higher rates. It does not seem likely that a sustained move higher will present itself, in my opinion – not yet at least. But the housing market has become conditioned to 4.70-5.00% rates and thus the reaction will not be kind to 5.00%-plus, and higher, that is inevitable over time.

Personal Income and Spending

The Commerce Department reported that personal income rose 0.4% in November (a bit below the expected 0.5% increase), which marks the fifth-straight monthly increase. Over the past year, overall personal income is down 0.3% -- although that has been helped by a 15% rise in government transfer payments. Total compensation (which excludes rental, dividend, interest and proprietors income) is down 2.2% y/o/y, but off by 5.6% when we exclude transfer payments.

All of the components looked good in November. Compensation was up 0.3%, same for wage & salary. Proprietors income rose 1.2%, boosted by another huge bounce on the farm side – up 23.0%; non-farm proprietors income rose 0.5% for the month. Rental income added 0.6% in November. Interest income rose 0.2% and dividend income was higher by 0.9%. Government transfer payments rose 0.5%. On a year-over-year basis, rental income and government transfer payments are the only segments that are positive.

On this transfer payments situation, we have seen massive increases in both actual $ amounts (as the social safety net has become larger, we’ve seen two rounds of stimulus checks, and higher SS outlays due to an aging population) and as a percentage of personal income. The spike over the past year is largely due to the French-style extensions of unemployment benefits that now extend to as much as 99 weeks.


In summary, the 0.3% bounce in the wage & salary component was welcome news and let’s hope this is the start of something good. Even if firms are unlikely to add aggressively to payrolls (and aggressive additions is what it will take to move the unemployment rate meaningfully lower over the next year), some decent increases to existing workers’ paychecks is not out of the question. Still, the overall figures (total income and compensation) are looking better than would otherwise be the case due to the transfer payments. Such activity, government spending at these levels, is not sustainable and that does boost the risk that we face another disappointing trend a few months out. The “Gods of the Copybook Heading” will prevail as they always do. Bret Stephens of the WSJ Editorial Board brought this up earlier in the week and reflecting on Rudyard Kipling’s poetic reminder that common sense always prevails is all the more apropos today.

On the spending side, personal expenditures rose 0.5% (also below the expectation, which estimated a 0.7% increase) as outlays for goods rose 1.4% (holiday shopping) and service rose 0.4%. The cash savings rate held steady at 4.7%.

University of Michigan Confidence

The U of M consumer confidence reading for December was revised down to 72.5 from the preliminary print of 73.4 that was release two weeks ago. Still, this shows that confidence did improve from November’s weak 67.4.


The economic outlook reading (expectations six months out) was also revised down to 68.9 from 69.7.


New Home Sales

New home sales tumbled 11.3% in November (a 1.7% increase was expected) after a big downward revision for October (up just 1.8% vs. the 6.8% rise initially reported last month) to 355,000 units at a seasonally-adjusted annual rate. This is the lowest level since April and erases most of the bounce from the January low of 329,000 units. On a year-over-year basis, new home sales are down 9%.


This offers us a glimpse of what will occur when the tax credit expires. (Unlike existing home sales that are counted when a contract closes, new home sales are counted when a contract is signed. That is, while existing sales are effectively counting activity a month or two in the past when the purchase process began, the new home sales figure measures what actually occurred in the reporting month. Since buyers in November largely believed the credit had essentially expired – had to close by November 30 – this offers a glimpse of what things may look like without the subsidy.)

By region, sales were flat in the Northeast, up 21% in the Midwest, down 21% in the South (this region makes up over half of the new-home market) and off by 10% in the West (the West and South together make up 73% of the new-home market).

The median price actually rose 3.8% in November to $217,400, which was quite unhelpful.

The supply of new homes, as measured by the inventory-to-sales ratio (the number of months it takes to sell off existing supply at the current sales pace) rose to 7.9 from 7.2 in October.

Yesterday I mentioned that we should be careful in our expectations regarding the supply of homes when referring to the previously-owned home figures. The supply of existing homes fell substantially and has returned to a level that is pretty close to the longer-term average. However, when foreclosures begin to hit the market that supply number will rise again. But that’s not all as the market is likely to be hit by a double whammy – more houses hitting the market due to foreclosures along with a decline in sales. If what has occurred in new home sales shows up in existing (although unlikely to fully occur until the tax credit expires in April) then it will boost the inventory/sales ratio that much more.

Futures

Stock-index futures are higher this morning. We await the jobless claims and durable goods orders reports. Unless these numbers are much worse than expected, traders appear determined to push prices higher. We continue to hold above that 50% retracement level we’ve referred to over the past two days.


Merry Christmas!


Brent Vondera, Senior Analyst

Monday, December 21, 2009

Santa Claus Rally

In the past, the stock market has made modest gains in late December into the beginning of early January. Widely recognized as the Santa Claus rally, this time period has quite the track record. Since 1950, the S&P 500 has increased an average of 1.5% during the seven trading days that start with Christmas Eve and end with the first two days in January. Stocks have gone up during this period in 12 of the last 15 years.

Other interesting facts (complements of InvesTech Research):

  • December is the best single month for stocks, with the S&P 500 index averaging a 1.6% gain. The first December after a bear market ends performs even better, averaging 3.1%.
  • November through January has historically been the best three-month span for stocks. The average gain over the last four decades from Nov. 20 through the end of January has been 4.2%, or an annualized rate of 23%.

There are several factors that people theorize are responsible for the Santa Claus rally such as peak retail season (due to holiday shopping), tax considerations, upbeat year-end investment reports (many of which have “top stocks for the next year”), happiness around Wall Street, people investing their Christmas bonuses, and vacationing Wall Street workers.

A prudent investor knows the Santa Claus rally is not an opportunity to make a quick buck (because that would be market timing!), but it’s difficult to ignore all together. After all, the lack of a Santa Claus rally in recent years has signaled turmoil lies ahead. The market tanked in 2000 when there was no Santa Clause rally in 1999 and a late-year drop two years ago preceded a disastrous 2009.

Is Santa Claus coming to town this year?


--

Peter J. Lazaroff, Investment Analyst